Build a Smart Excel Budget in 30 Minutes (Beginner Guide)
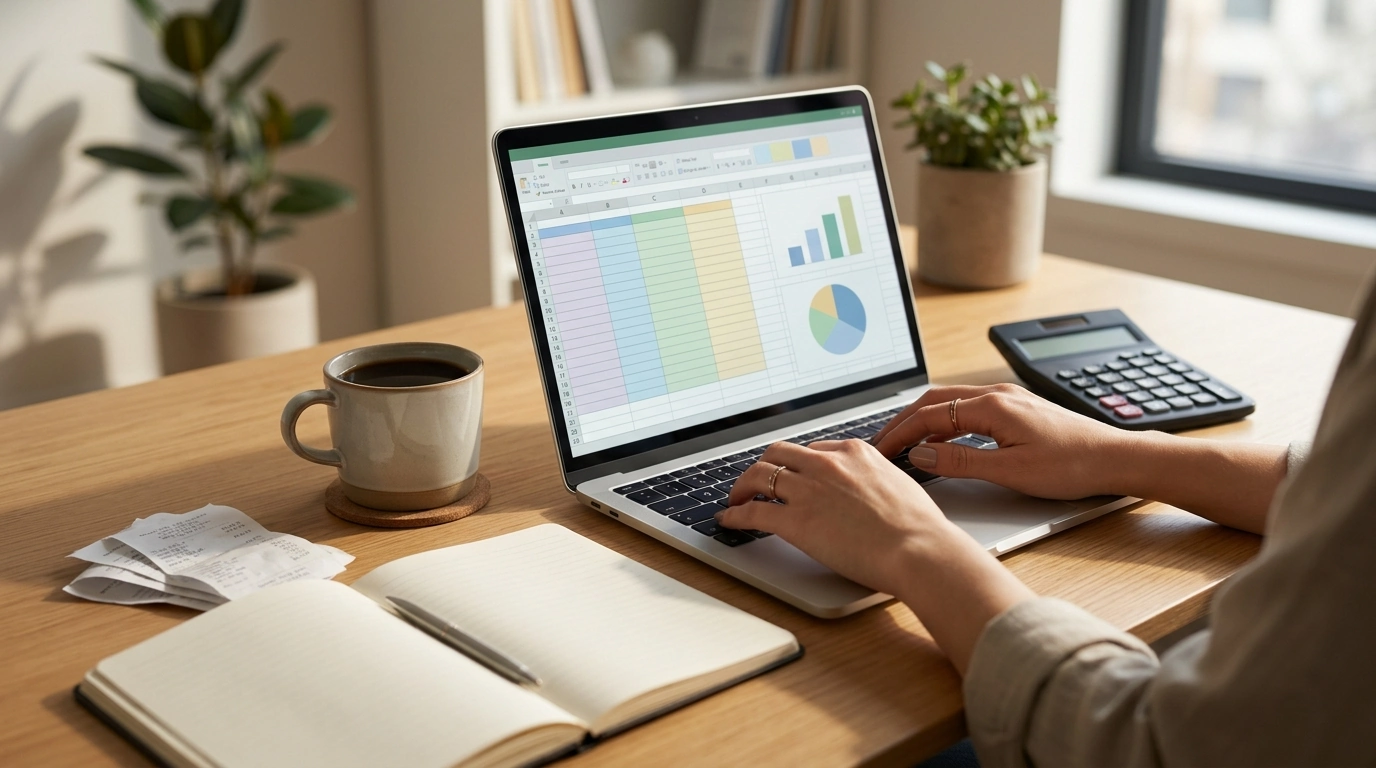
Excel Your Money: A Beginner-Friendly Smart Budget You Can Build in Excel
A practical Excel budget can replace guesswork with clear numbers: what comes in, what goes out, and what’s left for goals. The key is building a simple system you’ll keep using—one that updates fast, highlights issues early, and makes monthly planning feel manageable. Below is a beginner-friendly setup you can build in a single sitting, then improve over time with categories, formulas, and a quick monthly reset.
What a “smart” budget does (and what it avoids)
A smart Excel budget is less about fancy spreadsheets and more about consistent clarity. At its best, it:
- Tracks income, fixed bills, variable spending, and savings goals in one place.
- Shows a real-time remaining balance so decisions happen before money runs out.
- Uses categories to reveal patterns (not just one big total).
- Avoids over-complicated designs with too many tabs or constant manual math.
If a sheet takes longer to maintain than it saves, it won’t last. The smartest budget is the one you can actually update on a busy week.
Set up your workbook in 10 minutes
Create a new Excel file and start with three tabs. This keeps your budget clean while still giving you everything you need:
- Transactions: your single source of truth (every purchase, bill, paycheck).
- Budget: your planned monthly amounts by category.
- Summary: totals, remaining money, and category rollups.
Starter tab layout (recommended columns)
| Tab | Purpose | Key columns/fields |
|---|---|---|
| Transactions | Single source of truth for money in/out | Date; Description; Category; Amount; Type |
| Budget | Your monthly plan by category | Category; Planned; Notes |
| Summary | Monthly totals and remaining balance | Income total; Expense total; Remaining; Category rollups |
In the Transactions tab, keep expenses as positive numbers and use the Type column (Income/Expense) to separate them. This makes totals, charts, and troubleshooting much easier.
Build the core formulas (no advanced Excel required)
Once your columns exist, the goal is to stop manually adding. Two simple habits do most of the work:
- Turn your Transactions range into an Excel Table (select the range and press Ctrl+T). Your formulas will automatically expand as you add rows.
- Use SUMIFS to total income/expenses by month and category.
If you’re new to SUMIFS, Microsoft’s official reference is a helpful quick check for syntax: Microsoft Support: SUMIFS function.
Helpful formulas to copy and reuse
| Goal | Example formula | Tip |
|---|---|---|
| Total income for month | =SUMIFS(Transactions[Amount],Transactions[Type],”Income”,Transactions[Date],”>=”&A1,Transactions[Date],”<=”&EOMONTH(A1,0)) | Put the month start date in A1 |
| Total expenses for month | =SUMIFS(Transactions[Amount],Transactions[Type],”Expense”,Transactions[Date],”>=”&A1,Transactions[Date],”<=”&EOMONTH(A1,0)) | Keep expenses positive for easier reading |
| Category spent (monthly) | =SUMIFS(Transactions[Amount],Transactions[Category],$A5,Transactions[Type],”Expense”,Transactions[Date],”>=”&$B$1,Transactions[Date],”<=”&EOMONTH($B$1,0)) | A5 = category name; B1 = month start |
| Remaining | =Income_Total-Expense_Total | Add a savings line if preferred: subtract it too |
To prevent messy inputs, add Data Validation dropdowns for Category and Type. Clean data is what makes your Summary tab instantly trustworthy.
Choose categories that match real life
Categories are where budgets either become useful—or become a chore. Start with 8–15 categories and adjust after a month of real data.
- Fixed costs: rent/mortgage, insurance, phone, subscriptions.
- Variable essentials: groceries, gas/transportation, utilities.
- Discretionary: dining out, entertainment, shopping.
- Goals: emergency fund, debt payoff, investing.
- Sinking funds (irregular): car repairs, gifts, medical.
- Buffer: a small cushion to absorb “life happens” weeks.
If take-home pay varies, estimating net income can be easier when you understand withholding changes. The IRS tool can help you model impacts: IRS Tax Withholding Estimator.
Make data entry easy so you’ll actually use it
A budget only works when it stays current. Pick a routine that fits your week:
- Daily (2 minutes): log purchases quickly while they’re fresh.
- Twice weekly (10 minutes): paste in bank exports and categorize in a batch.
- Weekly clean-up: fix categories and descriptions so reports stay accurate.
If more than one person spends from the same accounts, add a Person column to Transactions. That one extra field makes filters and accountability dramatically easier.
For a simple budgeting baseline (especially when choosing categories), the Consumer Financial Protection Bureau’s worksheet can provide a helpful reference: CFPB Budget Worksheet.
Turn your budget into a dashboard you can read at a glance
Your Summary tab should answer three questions fast: How much came in? How much went out? What’s left? To make it “readable in seconds,” add:
Monthly review: the 15-minute reset
Recommended tools from our store
- Excel Your Money: The Beginner’s Guide to Creating a Smart Budget with Excel – How to Use Excel to Make a Budget Easily
- Corduroy Fabric Strap for Apple Watch (handy if you use watch reminders for “log transactions” check-ins)
- milanese-magnetic-stainless-steel-band-for-apple-watch (a comfortable option for daily wear during workouts, errands, and budgeting routines)
FAQ
What’s the easiest Excel budget setup for a complete beginner?
Use three tabs: Transactions, Budget, and Summary. Turn Transactions into an Excel Table and start with a few SUMIFS totals for income, expenses, and category spending—then improve it after your first month of real data.
Should expenses be entered as negative numbers in Excel?
Either works, but keeping expenses as positive numbers with a separate Type column (Income/Expense) often makes SUMIFS totals and charts easier to read. The most important rule is consistency so reports don’t break.
How often should a budget spreadsheet be updated?
Daily updates take about two minutes, or you can batch it twice per week in about ten minutes by pasting bank exports and categorizing. Add a 15-minute monthly review to reconcile and set next month’s plan.




Leave a comment